How Diaspora Kenyans Can Buy Apartments Remotely Securely
A US-based Kenyan buyer once paid KES 2 million toward a three-bedroom bungalow in Ruiru, marketed to him through a slick promotional video on a YouTube channel built specifically for diaspora Kenyans. By the time he hired a private investigator to check on construction progress, he discovered the land the developer had sold him didn’t actually belong to them. It belonged to a completely different company that had never agreed to sell it.
He eventually got his money back but only after months of legal pressure, and only a fraction of what he was initially offered. Many diaspora buyers in similar situations don’t get that far. Cases like this have been documented repeatedly across Kenyan investigative reporting: developers who register legitimate-looking companies, collect substantial deposits from diaspora buyers, and either stall construction indefinitely or turn out never to have owned the land in the first place.
This isn’t a rare, isolated story. It’s a documented, recurring pattern and diaspora Kenyans are, by a wide margin, the most deliberately targeted group in Kenya’s property fraud landscape. Here’s exactly how the scams work, and how to actually protect yourself while buying from thousands of miles away.
Why Diaspora Buyers Are Targeted So Specifically
Fraudulent developers tend to follow a strikingly consistent playbook, based on patterns identified across multiple documented fraud cases. They register legitimate-looking companies, rent professional offices in upscale Nairobi neighbourhoods, and produce polished marketing material sometimes including doctored images and falsified land registration numbers.
The reason diaspora buyers specifically are targeted isn’t incidental. Distance makes independent verification genuinely difficult, and many diaspora buyers are working multiple jobs abroad, sending money home, and simply can’t afford frequent trips to Kenya to physically inspect a property before paying for it. Fraudulent developers also lean heavily on emotional marketing appealing directly to the desire to own a home “back home,” particularly framed around retirement, which makes buyers more likely to move fast rather than pause for full due diligence.
One documented tactic worth knowing specifically: some fraudulent developers sponsor diaspora-focused YouTube channels to create an illusion of trustworthy, independent coverage — when the channel is, in effect, part of the marketing operation itself.
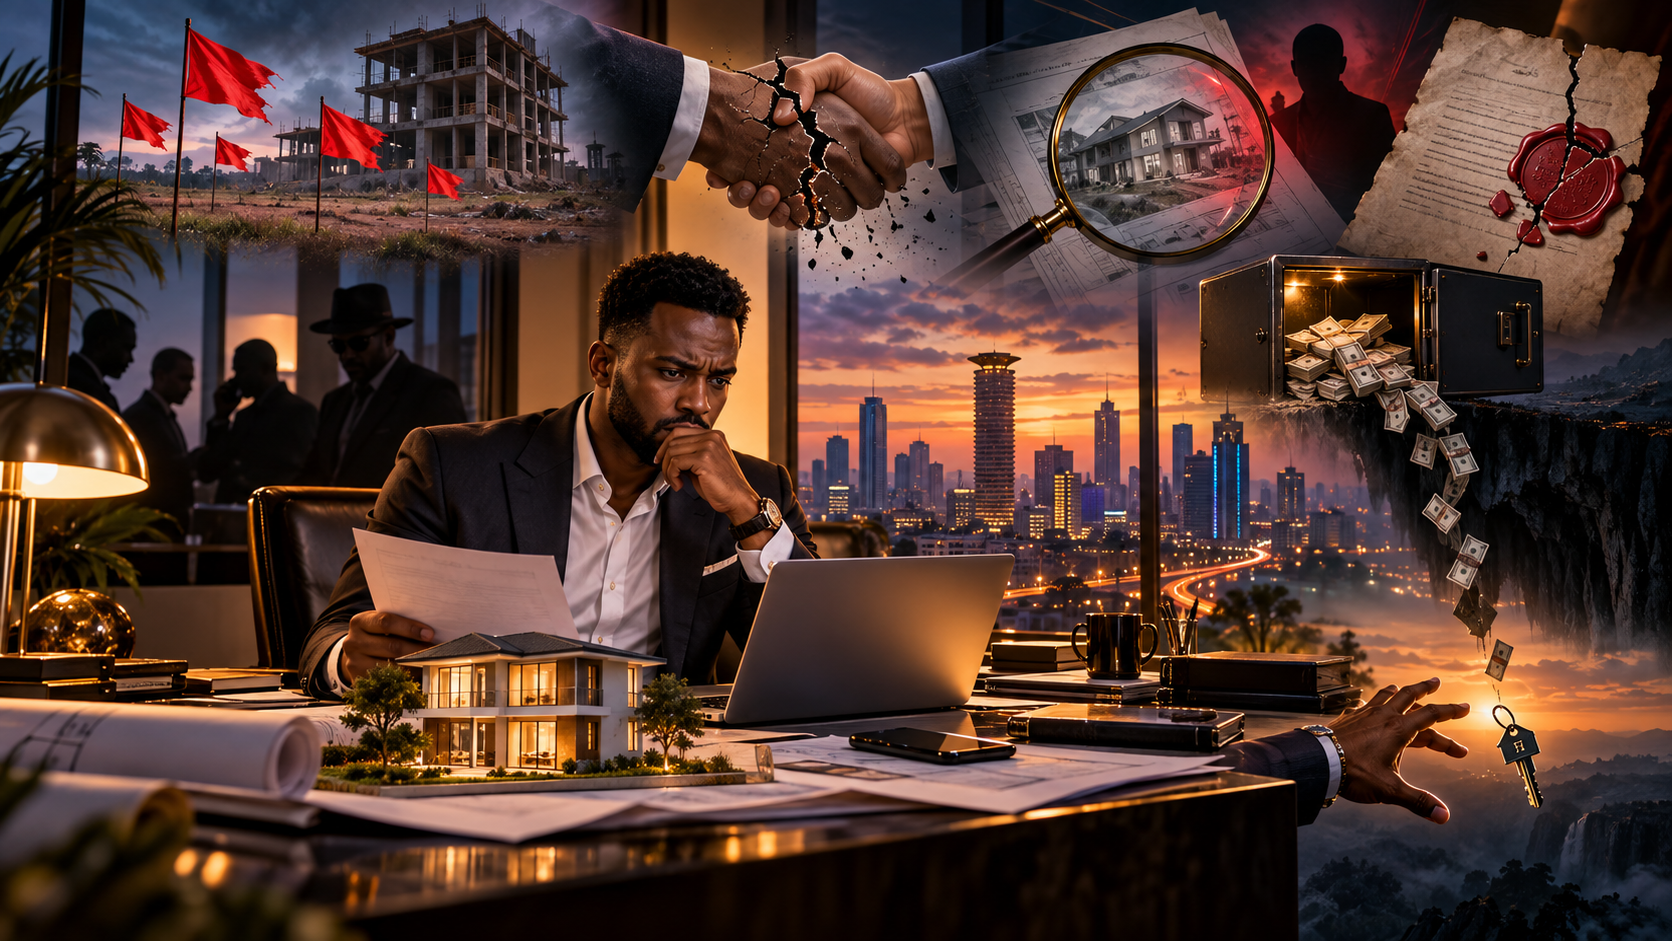
The Red Flags That Show Up Before the Money Disappears
Based on patterns identified across multiple documented fraud cases, a few warning signs show up again and again:
- Unrealistic completion timelines —promises of finished construction within 30–90 days for a full residential project should be treated with real skepticism
- Pressure to pay large sums upfront — legitimate developers rarely demand deposits exceeding 10% of the purchase price before any construction has meaningfully progressed
- Reluctance to use an escrow account or advocate’s client trust account — this is one of the clearest signals. A developer unwilling to hold your money in a regulated third-party account until agreed milestones are met is asking you to trust them entirely on faith
- Inconsistent or vague answers about land ownership — if a developer can’t produce a clean, verifiable title in the actual name of the entity you’re contracting with, that’s disqualifying, not a detail to overlook
- Marketing that leans heavily on emotion over documentation — glossy video content and testimonials are not a substitute for a title search
The Step-by-Step Process for Buying Remotely, Safely
1. Appoint your own independent advocate, registered with the Law Society of Kenya — before any money changes hands. Not the developer’s recommended lawyer, not the seller’s. Your own, with no financial relationship to the other side of the transaction. This single step is the most consistently cited protection across every diaspora buying guide currently published, and it’s the one corner fraudulent developers most want buyers to cut.
2. Conduct an independent title search. Your advocate should verify the registered owner of the land through the Ministry of Lands, confirming there are no disputes, competing claims, or existing charges against the property and critically, that the seller in your sale agreement is the actual registered owner, not a related company or an agent acting without clear authority.
3. Use Ardhisasa to verify records digitally where possible. Kenya’s land registry has moved substantially online, and foreigners and diaspora buyers can now use dedicated Ardhisasa accounts to verify titles and track transfers remotely reducing (though not eliminating) the need to be physically present for this step.
4. Insist on an escrow arrangement or advocate’s trust account for your payments. Rather than paying a developer directly, funds held by an independent third party and released only when specific, verifiable construction or transaction milestones are met dramatically reduces your exposure if something goes wrong.
5. Use virtual tours and video walkthroughs — but don’t treat them as a substitute for independent verification. Digital property tours have genuinely closed a major information gap for diaspora buyers, letting you assess a property in detail without being present at every stage. But a virtual tour tells you what a unit looks like it tells you nothing about who legally owns the land underneath it.
6. If buying off-plan, weigh the payment structure against the real risk. Off-plan flexible payment plans can be a genuinely good fit for a diaspora income model converting remittances into an asset gradually rather than sending money home with no structured destination. But a flexible payment plan is not, by itself, evidence that a project is safe. The same due diligence applies regardless of how attractive the installment structure looks.
7. Confirm what you’re legally allowed to own before you fall in love with a specific property. Foreigners and diaspora Kenyans who have changed citizenship can generally hold property on leasehold tenure (typically up to 99 years), but cannot own agricultural land under freehold title without special government approval. Kenyan citizens living abroad who haven’t changed citizenship retain full ownership rights, including freehold, the same as any resident Kenyan.
Financing Options Available to Diaspora Buyers
Several major Kenyan banks now operate dedicated diaspora mortgage programmes, including KCB, Stanbic, and Standard Chartered, allowing diaspora Kenyans to finance a purchase rather than paying entirely in cash. Diaspora buyers meeting eligibility criteria are also able to register and apply through the government’s Boma Yangu affordable housing platform, which for those who qualify remains one of the more affordable formal routes to homeownership in Kenya.
Whichever financing route you use, be mindful of currency exchange timing specifically. Exchange rate movement between the day you commit to a price and the day funds actually transfer can meaningfully change what a property costs you in your home currency, particularly for larger transactions.
A Realistic Bottom Line
Kenya’s property market remains a genuinely strong opportunity for diaspora investors the combination of relatively high rental yields, currency dynamics, and deep personal and family ties to the market is difficult to replicate elsewhere. But the same features that make diaspora buyers an attractive market for legitimate developers make them an equally attractive target for fraudulent ones.
The difference between the two isn’t intuition or luck. It’s whether you had your own independent lawyer, verified the title yourself, and refused to send significant money to anyone without a regulated third party holding it until agreed conditions were actually met. Every documented fraud case that’s become public reporting shares at least one of those steps having been skipped.
FAQs
Can diaspora Kenyans legally buy apartments in Kenya?
Yes. Kenyan citizens living abroad retain full ownership rights including freehold. Foreign nationals or those who’ve changed citizenship can generally buy property under leasehold tenure, typically up to 99 years, though foreigners cannot own agricultural land under freehold without special government approval.
What’s the single most important step to avoid a real estate scam as a diaspora buyer?
Appointing your own independent advocate registered with the Law Society of Kenya, with no financial relationship to the seller or developer, before any money is paid.
How can I verify a property’s title without being physically in Kenya?
Your independent advocate can conduct a title search through the Ministry of Lands, and Kenya’s Ardhisasa platform now allows verification of land records digitally, including dedicated accounts for foreigners and diaspora buyers.
Are flexible off-plan payment plans a sign that a project is trustworthy?
No. A flexible or attractive payment structure is not evidence of legitimacy on its own. The same due diligence title verification, escrow arrangements, developer track record should apply regardless of how appealing the payment terms look.
Can I get a mortgage from a Kenyan bank while living abroad?
Yes. Several major banks, including KCB, Stanbic and Standard Chartered, operate dedicated diaspora mortgage programmes for Kenyans living abroad.
What should I do if a developer refuses to use an escrow account or advocate’s trust account?
Treat it as a serious warning sign. Legitimate developers generally have no objection to funds being held by a regulated third party and released against verified milestones reluctance to do so is one of the most consistently documented red flags in fraud cases involving diaspora buyers.